 Chat GPT
 Mistral
 Claude
 Perplexity
 Grok
Key points:
- From September 2026, foreign companies registered for French VAT will be required to transmit certain transaction data through the e-reporting system.
- Unlike e-invoicing, e-reporting also applies to companies not established in France where they carry out transactions taxable in France.
- The requirements vary according to the size of the company (large enterprises/intermediate-sized enterprises from 2026, SMEs/micro-enterprises from 2027) and the nature of the transactions (B2B, B2C, payments, reverse charge, etc.).
- Data must be transmitted via an approved platform (PA) or another compliant technical service provider.
The French e-invoicing reform is gradually entering its operational phase. While the e-invoicing requirement mainly concerns domestic transactions between businesses established in France, e-reporting also applies to foreign companies with a French VAT number.
From 1 September 2026, foreign companies subject to VAT in France will be required to transmit certain transaction data and, where applicable, payment data to the French tax authorities as part of the new e-reporting system.
This development represents a major change in the management of VAT reporting obligations.
Which companies are affected? Which transactions must be reported? What are the risks of non-compliance? How can you prepare for this new tax requirement?
Here is everything foreign companies need to know about e-reporting requirements in France.
What is e-reporting in France?
E-reporting is an electronic system for transmitting tax data to the French administration.
It complements the mandatory e-invoicing system introduced as part of the VAT reform. Its purpose is to give the French tax authorities a more comprehensive view of economic transactions carried out in France.
Unlike e-invoicing, which is based on the exchange of electronic invoices between businesses established in France, e-reporting covers transactions that cannot be covered by this system.
The data transmitted is used in particular to:
- strengthen the fight against VAT fraud;
- prepare for the future pre-filling of French VAT returns;
- facilitate tax audits;
- improve the quality of the data collected by the administration;
- modernise exchanges between businesses and public authorities.
“The objective is to gain a better understanding of economic activity in real time, reduce blind spots and strengthen the fight against fraud, particularly VAT fraud.”
Sébastien Rabineau – French tax authorities (DGFiP) (Directorate-General for Public Finance)1
E-invoicing and e-reporting: what are the differences?
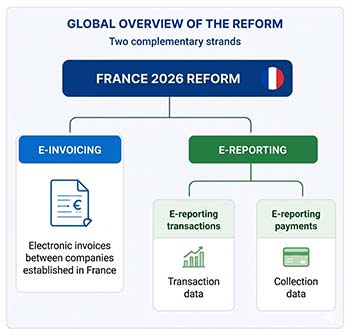
The French e-invoicing reform, which will enter into force on 1 September 2026, has two distinct components:
- e-invoicing;
- e-reporting.
E-reporting itself is divided into two categories:
- e-reporting of transaction data;
- e-reporting of payment data.
This distinction is particularly important for foreign companies with a French VAT number.
Unlike companies established in France, foreign companies without a permanent establishment in France are not required to issue or receive electronic invoices through the French e-invoicing system.
The legislator has reserved this requirement for transactions carried out between businesses established in France.
Thus, a German, Italian, Spanish, British or US company that only has a French VAT number will not be required to receive or issue French electronic invoices under e-invoicing.
However, the same company may be subject to the e-reporting requirement where it carries out certain transactions taxable in France.
The French tax authorities (DGFiP) have also published a page2 dedicated to the e-reporting requirements of foreign companies without a permanent establishment in France, confirming that these companies may be subject to data transmission when they carry out transactions subject to French VAT.
For non-resident companies, this distinction is one of the key aspects of the reform.
| Requirement | Company established in France | Foreign company not established in France but registered for French VAT |
|---|---|---|
| Receipt of electronic invoices | Yes | No |
| Issuance of electronic invoices | Yes | No |
| Transaction e-reporting | Yes (extended depending on the transactions)* | Yes (limited depending on the transactions)** |
| Payment e-reporting | Yes (extended depending on the transactions)* | Yes (limited depending on the transactions)** |
* Yes (extended): requirement covering all transactions concerned by the reform.
** Yes (limited): requirement limited to certain transactions carried out by companies not established in France but registered for French VAT.
For foreign companies registered for French VAT, e-reporting is therefore the main requirement arising from the 2026 e-invoicing reform.
Who is subject to e-reporting in France in 2026?
This requirement applies to foreign companies registered for French VAT that carry out transactions taxable in France.
These include in particular:
- companies holding stock in France;
- companies making domestic sales in France;
- foreign e-commerce sellers or marketplace operators, excluding businesses using OSS;
- companies carrying out intra-EU acquisitions or domestic purchases subject to the reverse charge mechanism.
“This far-reaching reform of the economy is an opportunity for companies to take a step back and reassess how they operate.”
Laure Collignon – French tax authorities (DGFiP) – Directorate-General for Public Finance (Business Support Service)3
What is the e-reporting timetable for companies established outside France?
The timetable applicable to foreign companies follows the same deadlines as those provided for under the e-invoicing reform.
| Date | Requirement |
|---|---|
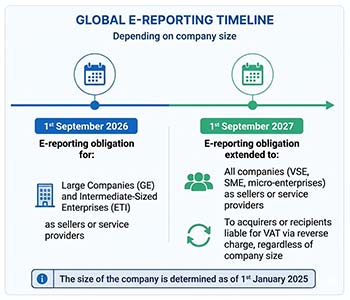
| 1 September 2026 | E-reporting for large enterprises (GE) and intermediate-sized enterprises (ETI) |
| 1 September 2027 | Extension to small and medium-sized enterprises (SMEs), very small enterprises (TPEs) and micro-enterprises |
The effective date depends on the size of the company, not its nationality.
How is the size of the company determined?
The size of the company is assessed as at 1 January 2025.
The assessment is based on the last financial year closed before that date or, failing that, on the first financial year closed after that date.
A foreign company will be subject to e-reporting from 1 September 2026 if it meets at least one of the following criteria:
| Criterion | Threshold |
| Number of employees | 250 employees or more |
| Turnover and total assets | More than €50 million and more than €43 million |
Which transactions will be subject to transaction e-reporting?
Article 290 II of the French General Tax Code provides that taxable persons established outside France must provide specific information on their transactions to the French tax authorities when their activities in France are subject to French VAT.
From 1 September 2026, the system applies to supplies of goods and services taxable in France made to:
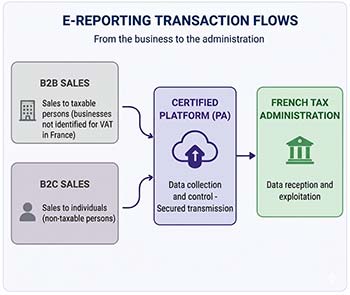
- Taxable entities (B2B) not registered for VAT in France;
- Non-taxable customers (B2C).
This requirement applies where the transactions are not already reported under a One Stop Shop (OSS) scheme (EU OSS or non-EU OSS).
From 1 September 2027, the scope will be extended to transactions subject to the reverse charge mechanism, including intra-EU acquisitions and domestic purchases subject to reverse charge.
Examples of transactions subject to e-reporting for non-resident companies
The most common cases are as follows:
| Transaction | Transaction e-reporting | Payment e-reporting | Large enterprises / ETIs | SMEs / micro-enterprises |
|---|---|---|---|---|
| Sale of goods taxable in France (excluding OSS) | Yes | In the event of a deposit | 09/26 | 09/27 |
| Sale of services taxable in France (excluding EU/non-EU OSS) | Yes | Yes | 09/26 | 09/27 |
| Intra-EU supply | No | No | — | — |
| Intra-EU acquisition | Yes | No | 09/27 | 09/27 |
| Exports | No | No | — | — |
| Sales subject to reverse charge (Art. 283-1 para. 2 of the French General Tax Code) | No | No | — | — |
| Purchases subject to reverse charge (Art. 283-1 para. 2 of the French General Tax Code) | Yes | No | 09/27 | 09/27 |
| Sales of subcontracted construction services (Art. 283-2 nonies of the French General Tax Code) | No | No | — | — |
| Purchases of subcontracted construction services (Art. 283-2 nonies of the French General Tax Code) | Yes | No | 09/27 | 09/27 |
| Import of goods | No | No | — | — |
| Intra-EU distance sales (OSS) | No | No | — | — |
| Exempt transactions | No | No | — | — |
Which transactions are excluded from the system?
Not all transactions are covered.
In particular, foreign companies do not have to report:
- exempt intra-EU supplies;
- exports to countries outside the European Union;
- distance sales already reported through OSS;
- certain transactions covered by special schemes that are already subject to other reporting mechanisms.
These transactions continue to be reported under the usual tax procedures, but are outside the scope of e-reporting.
In which cases must payment data not be transmitted?
Two main situations make it possible not to apply this requirement:
The company has opted for VAT on a cash basis
In this case, VAT becomes due when the invoice is issued rather than when payment is received.
Payment data transmission is therefore not required.
The customer is liable for VAT
Where the reverse charge mechanism applies, the supplier is not liable for VAT.
Collection data therefore does not have to be reported.
What data must be transmitted as part of e-reporting?
The data required by the administration mainly concerns transactions and payments.
The exact content depends on the nature of the transactions carried out.
Simplify your e-reporting compliance with MyASD
With MyASD and its ASD Taxflow module, you can centralise your VAT data and ensure compliance with your e-reporting obligations.
B2C transaction e-reporting
| Data to be transmitted | Description |
|---|---|
| Supplier’s SIREN | Reporting company’s identifier |
| Period | Period covered by the return |
| Current date | Transmission date |
| Number of transactions | Total transactions carried out |
| Transaction category | Goods, services, intra-EU transactions or margin scheme VAT |
| Amount excluding VAT | Daily total of transactions excluding tax |
| VAT amount | Corresponding VAT, by rate |
| Option for VAT on a cash basis | Where applicable |
B2B transaction e-reporting
| Data to be transmitted | Description |
|---|---|
| Supplier’s SIREN or VAT number | Seller identification |
| Customer’s SIREN or VAT number | Buyer identification |
| Supplier’s country | Country of establishment |
| Customer’s country | Country of establishment |
| Nature of the transaction | Sale of goods (LB), supply of services (PS) or mixed transaction (LBPS) |
| Invoice date | Invoicing date |
| Invoice number | Invoice reference |
| Total excluding VAT by rate | Amounts excluding VAT broken down by VAT rate |
| VAT amount by rate | VAT broken down by rate |
| VAT rate | Applicable rates |
| Total invoice amount excluding VAT | Total excluding tax |
| Total invoice VAT | Total VAT |
| Currency | Currency used |
| Tax representative number | Where applicable |
| Reference to the corrected invoice | In the event of a credit note or correction |
| Option for VAT on a cash basis | Where applicable |
| Reference to VAT exemption | Where applicable |
| Reference to a special scheme | Example: margin scheme VAT |
| Date of delivery or completion of the service | Transaction date |
| Deposit date | If different from the invoice date |
| Specific mentions | Reverse charge, self-billing or single taxable person |
Payment e-reporting (non-resident companies)
B2C payments
| Data to be transmitted |
|---|
| SIREN of the collecting entity |
| Current date |
| Total amount collected by VAT rate |
| Period covered |
B2B payments
| Data to be transmitted |
|---|
| SIREN of the collecting entity |
| Current date |
| Total amount collected by VAT rate |
| Period covered |
| Invoice number |
The French tax authorities have defined standardised transmission formats to ensure the consistency of the data collected.
Companies will therefore need to ensure the quality of the information generated by their accounting systems and ERP systems.
How often must you transmit e-reporting data according to your VAT scheme?
The 2026 French reform provides for the transmission of two distinct categories of data: transaction data and payment data. The requirements vary according to your VAT scheme.
Monthly standard VAT scheme
For transaction data:
Companies under the monthly standard VAT scheme must transmit transaction data every ten days and payment data once a month.
Quarterly standard VAT scheme
For transaction and payment data:
Companies under the quarterly standard VAT scheme must transmit transaction and payment data every month.
The detailed deadlines are shown in the table below:
| VAT scheme | Transaction data transmission | Payment data transmission | ||
|---|---|---|---|---|
| Transmission frequency | Transmission deadline | Transmission frequency | Transmission deadline | |
| Monthly standard VAT scheme | 3 transmissions per month (in ten-day periods) : – Period 1: from the 1st to the 10th – Period 2: from the 11th to the 20th – Period 3: from the 21st to the end of the month | 10 days after the end of the ten-day period: i.e. the 20th, the 30th of the month and the 10th of the following month. *except in February | Monthly | By the 10th of the following month |
| Quarterly standard VAT scheme | Monthly | By the 10th of the following month | Monthly | By the 10th of the following month |
What penalties apply in the event of non-compliance with e-reporting obligations?
Failure to comply with reporting obligations is subject to penalties under Article 1788 D I and II of the French General Tax Code4.
The French tax authorities may impose:
- a €500 fine for each missing or incorrect return;
- up to a maximum of €15,000 per calendar year.
How can you prepare your company for the 2026 deadline?
E-reporting is an important step in the modernisation of the French tax system. Foreign companies with a French VAT number must start preparing now to remain compliant and safeguard their activities in the French market.
Preparations should begin well before the requirements come into force, as compliance projects generally require several months of work.
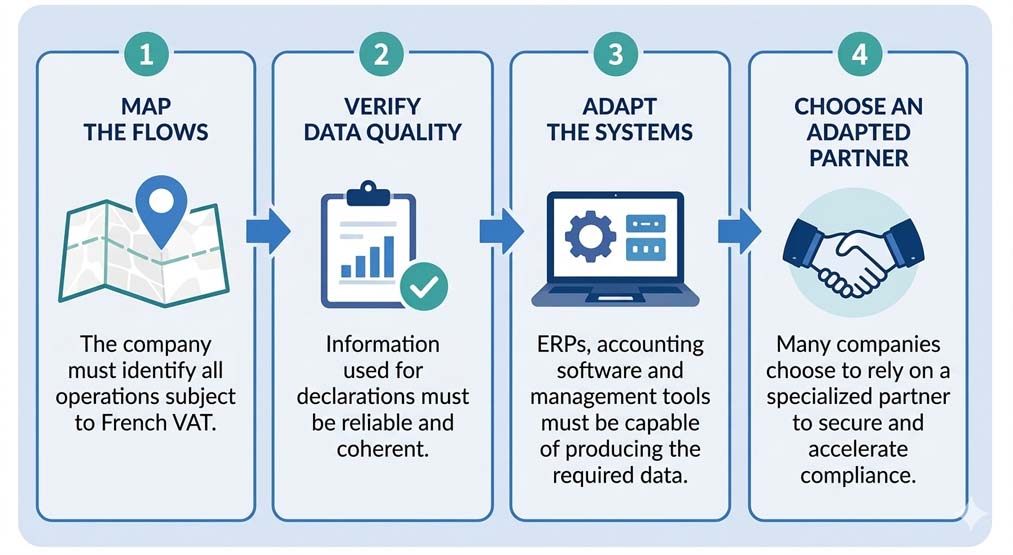
This process generally involves several steps:
- identify and map transactions subject to French VAT;
- check the quality and reliability of the data used;
- adapt systems (ERP, accounting software, management tools) to generate the required information;
- choose a suitable partner to ensure compliance.
Conversely, waiting until the final months may result in:
- additional costs;
- technical difficulties;
- risks of non-compliance;
- delays in data transmission.
Why must foreign companies use an approved platform?
Unlike certain current reporting obligations, e-reporting data cannot be transmitted directly to the French tax authorities.
Foreign companies concerned must use an approved platform (PA) (in other words, a partner dematerialisation platform (PDP)), which will provide:
- data collection;
- consistency checks;
- format conversion;
- secure transmission of information to the French tax authorities.
Choosing a technical partner is therefore a strategic decision for non-resident companies.
An in-depth analysis of French VAT flows, reporting obligations and existing information systems is essential to ensure compliance before the 2026 and 2027 deadlines.
ASD Group supports you with your e-reporting compliance
In this context, ASD Group supports non-resident companies registered for French VAT in determining their obligations and implementing e-reporting in practice.
As e-reporting data must be transmitted via an approved platform (PA), ASD Group has partnered with such a platform to offer its clients a solution that complies with the requirements of the French tax authorities.
Check with us whether you are subject to e-reporting in France
ASD Group supports you in ensuring your compliance and helps you prepare for your e-reporting obligations in France from the outset.
Sources:
- itforbusiness.fr (in French) ↩︎
- French tax authorities (DGFiP) note (in English) ↩︎
- aucoeurduchr.fr (in French) ↩︎
- Article 1788 D I and II of the French General Tax Code (in French) ↩︎