E-Reporting in France: How does it work for foreign companies subject to VAT? Learn more
VAT Rates in Europe in 2026 Learn more

HOME > E-REPORTING IN FRANCE

E-Reporting in France:
Ensure full compliance for your non-resident company

Is your company registered for French VAT but not established in France? You may be affected by France’s e-reporting requirements. ASD Group supports you in ensuring compliance.

Large Enterprises and Mid-sized Companies

Reform in force since
1 September 2026

SMEs and Micro-enterprises

00 days

until it comes into force on
1 September 2027
Understanding the reform

What is e-reporting and how can it concern your non-resident company?

E-reporting is an electronic system for transmitting tax information to the French tax authorities. It complements the mandatory electronic invoicing regime (e-invoicing) in order to provide the authorities with a more complete view of economic activity carried out in France.

While electronic invoicing is limited to exchanges between companies established in France, e-reporting extends to non-resident companies as soon as they carry out taxable transactions in France under their French VAT number.

Does e-reporting apply to your company?

Non-resident companies registered for VAT in France and carrying out taxable transactions in the territory are concerned.

⚠️ Important point

A non-resident company that does not have a French VAT number does not fall within the scope of e-reporting obligations.

The entry into force date depends on the size of the company, and not on its country of origin.

Understanding the reform

From when does the obligation apply to your company?

Non-resident companies registered for VAT in France that carry out taxable transactions in France are concerned.

Does your company meet one of the following thresholds?

Meeting just one of these criteria is sufficient to trigger the obligations as of 1st September 2026.

250 employees

or more

OR

€50 million

of turnover or more

AND

€43 million

of total balance sheet or more

If none of these thresholds is met, the obligation starts on 1st September 2027.

Our support

Three steps, with no effort on your part

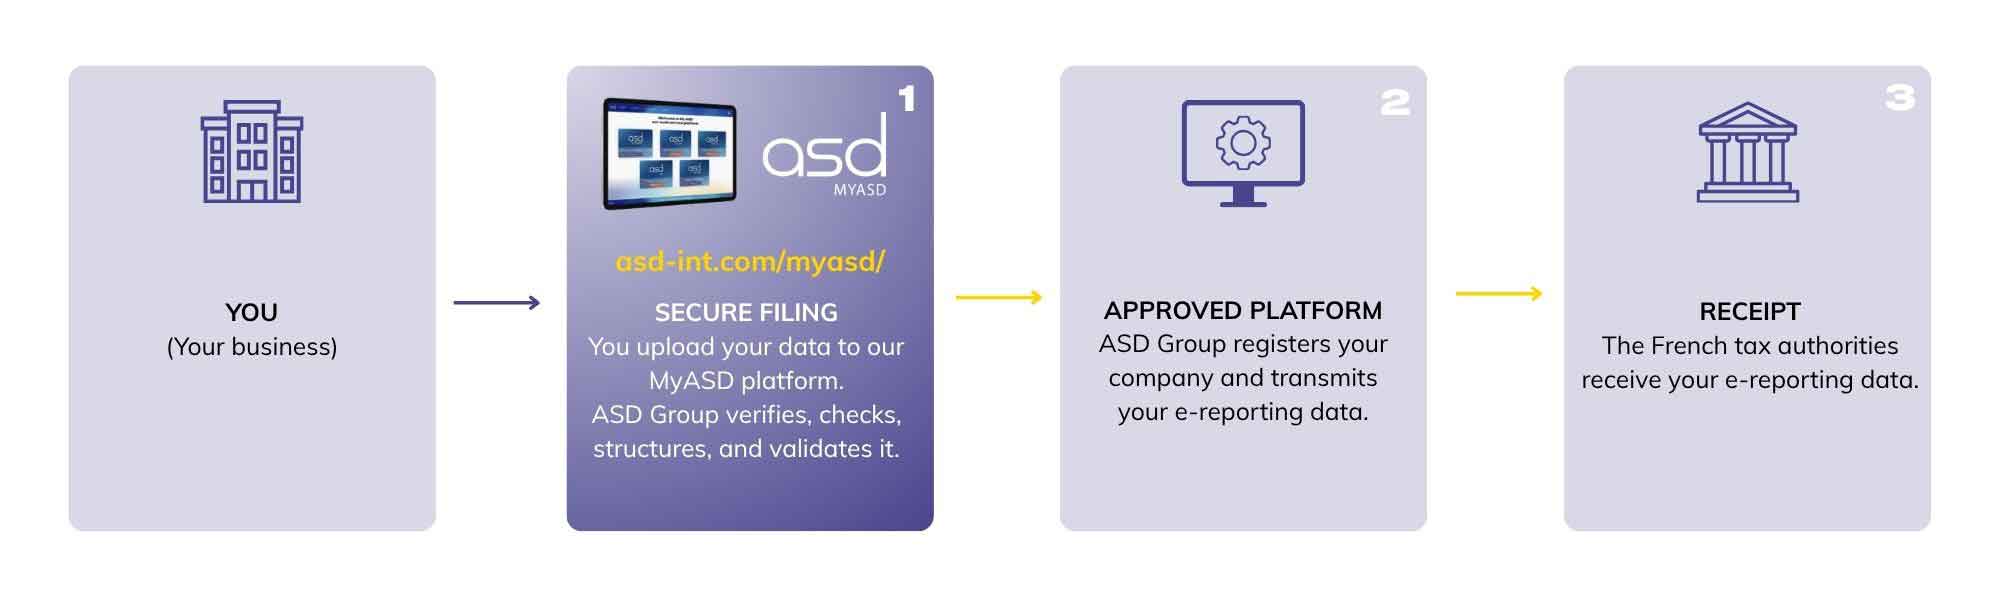
ASD Group handles the entire e-reporting process on your behalf, from data collection through to final transmission via the certified platform.

01

Data collection

Upload via MyASD

You simply upload your transaction data files to your secure MyASD client area. Our specialists then check, organise and validate each data flow before transmission.

02

Official registration

Registration with the partner certified platform

ASD Group registers your company on the certified platform (PA) of our certified partner, the only legal route open to non-established entities.

03

Official transmission

Transmission of e-reports

ASD Group transmits your e-reporting data to the French tax authorities (DGFiP) via the certified platform, in compliance with the legal deadlines and required formats, while archiving acknowledgements of receipt and ensuring compliance monitoring.

Stakes and risks

What risks in the event of non-compliance?

The French tax authorities may impose significant penalties in the event of failure to meet e-reporting obligations. These sanctions apply per transaction and are cumulative.

Financial penalties

Operational risks

Certified platform

Why must non-resident entities use a certified platform (PA)?

The public platform (public invoicing portal, PPF) is only accessible to entities established in France. Non-resident companies registered for VAT in France have no choice but to use a certified platform approved by the French tax authorities (DGFiP).

Access limited to certified platforms (PA)

Companies not established in France cannot register directly on the Public Invoicing Portal (PPF). Only a certified platform (PA) allows them to fulfil their legal obligations.

Partner approved by the French tax authorities (DGFiP)

ASD Group collaborates with an approved partner certified platform certified by the French tax authorities (DGFiP). The compliance of each transmission is guaranteed.

Transmission within deadlines

E-reporting data must be transmitted at regular intervals (within the legal deadlines linked to the declaration frequency). ASD Group guarantees compliance with deadlines and archives each acknowledgement of receipt.

Regulatory calendar

The critical deadlines not to miss

The French electronic invoicing reform will be rolled out in successive stages. For non-resident entities without an establishment in France, the e-reporting obligation applies from the initial phase. The start date depends solely on the size of the company, and not on its nationality.

1st September 2026

Large companies — first phase

E-reporting obligation for large companies registered for VAT in France. Non-established entities are subject to this obligation as of this date, with no size-related exemption.

1st September 2027
Intermediate-sized enterprises (ETI) and foreign SMEs — second phase

Extension of the e-reporting obligation to non-resident companies classified as intermediate-sized enterprises (ETI) and SMEs.

Immediate action

Registration with a certified platform (PA), configuration of data flows and technical tests may take several weeks. Postponing preparations until the last minute exposes you to penalties from the first month.

Network of 20 offices in Europe and beyond
0
Presence in 18 countries in Europe and beyond
0
Countries covered
0
Employees worldwide
0
Client companies in industry, retail, e-commerce and more
0
Advantages

Why entrust your e-reporting to ASD Group?

The advantages for you: simple and secure management of your tax obligations in France:

Our commitment:
Your e-reporting compliance, assured for every declaration period.

ASD Group is your single point of contact for all obligations linked to the French electronic invoicing reform. Our VAT specialists coordinate all stakeholders (partner certified platform, your accounting teams, French tax authorities) so that you have no administrative tasks to manage.

Our areas of expertise

How ASD Group
can support you

ASD Group supports French and international companies in the complete management of their tax and customs obligations.

International VAT

Tax representation

Customs & Trade

Audit & Compliance

Frequently asked questions

E-reporting in France:
the questions we are asked most often

Everything non-resident companies registered for VAT in France need to know about their new e-reporting obligations.

E-reporting is an electronic system for transmitting tax data to the French authorities. It complements electronic invoicing by giving the French tax authorities (DGFiP) a more complete view of economic activity carried out in France.

Yes, provided that it is registered for VAT in France and carries out taxable transactions in the territory (distance sales to private individuals, B2C services, or transactions outside the electronic invoicing regime). Without a French VAT number, the company is not concerned.

Electronic invoicing only concerns transactions between companies established in France. E-reporting also applies to non-resident companies as soon as they carry out taxable transactions in France under their French VAT number.

As of 1st September 2026 if at least one of these thresholds is met: 250 employees or more, or €50 million of turnover associated with €43 million of total balance sheet. Otherwise, the obligation starts on 1st September 2027.

Large companies and foreign intermediate-sized enterprises registered for VAT in France; non-established entities do not benefit from any size-related exemption as of this date.

They become subject to the obligation as of 1st September 2027, when the regime is extended to intermediate-sized enterprises and SMEs.

No. It depends solely on the size of the company (workforce, turnover and total balance sheet), and not on the country of origin.

Distance sales of goods to private individuals in France, B2C services performed in France, and more generally all transactions not covered by electronic invoicing (B2C or outside the EU).

The PPF is reserved for entities established in France. Non-resident companies must use a certified platform (PA) certified by the French tax authorities (DGFiP).

It is a platform certified by the French tax authorities (DGFiP) and constitutes the only legal channel through which non-established entities can transmit their e-reporting data.

The files are produced in the prescribed JSON and XML formats before being transmitted to the French tax authorities (DGFiP) via the certified platform.

A fine of €500 for each missing or incorrect transmission (capped at €15,000 per year), late payment penalties, increased fines in the event of repeated failures, and a risk of tax reassessment or audit.

Without a PA, transmission is technically impossible; data may be rejected due to format errors; and inconsistencies in data flows may trigger a tax audit.

In three steps: collection and validation of your data via MyASD, official registration of your company with the partner certified platform, and transmission of e-reports to the French tax authorities (DGFiP) with archiving of acknowledgements of receipt.

You upload your accounting exports or sales files directly to your secure MyASD client area; our team then checks, structures and validates each data flow.

ASD Group registers your company with the partner PA, provides the required supporting documents, configures your company’s account and carries out the technical compliance tests.

Registration with a PA, configuration of data flows and technical tests may take several weeks; it is recommended not to leave these steps until the last minute.

Your French VAT registration, the transaction flows concerned, then start registration with a PA and configuration of data transmission via MyASD.

Questions about your particular situation?

Our specialists support you at every stage of your e-reporting compliance in France.

International scope

We operate in more than 30 countries

Our teams perfectly master the VAT rules of each territory.

Austria

Belgium

Bulgaria

Cyprus

Croatia

Czechia

Denmark

Estonia

Finland

France

Germany

Greece

Hungary

Ireland

Italy

Latvia

Lithuania

Luxembourg

Malta

Netherlands

Norway

Poland

Portugal

Romania

Slovakia

Slovenia

Spain

Sweden

Switzerland

United Kingdom

partners worldwide
0
years of experience in supporting companies in their international activities
0
languages
0
of our clients recommend us
0 %

Do not let e-reporting in France
become a risk for your company

As of 1st September 2026, every undeclared transaction exposes your company to penalties. Setting up the service requires several weeks: do not leave it until the last minute. Entrust your e-reporting to ASD Group today.

They trust us

E-Reporting in France

From 1 September 2026 · Foreign large and mid-sized companies, get ready! More info